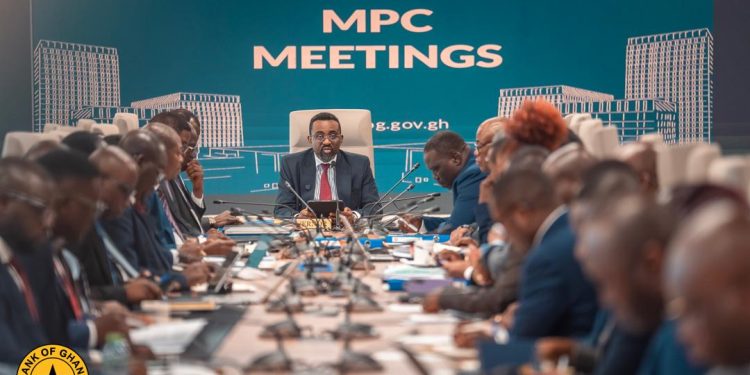
The Bank of Ghana has realigned its Monetary Policy Rate from 14% to 11%, representing a 300-basis-point adjustment, as it moves to align its policy benchmark with prevailing market interest rates.
Announcing the decision after the 133rd Monetary Policy Committee meeting in Accra on Wednesday, November 18, Governor Dr Johnson Pandit Asiama explained that the adjustment was not a conventional rate cut but a realignment of the policy rate to reflect conditions in the money market.
He said prevailing market rates had already fallen below the existing 14% policy rate, creating a disconnect between the announced benchmark and the actual cost of money in the market.
“As a result, prevailing market rates have evolved at levels below the current monetary policy rate, indicating that the effective policy stance is actually lower than the announced rate,” he said.
The Governor explained that the Bank had identified a gap between the announced policy rate and prevailing market rates, prompting changes to its monetary operations framework to improve the transmission of monetary policy signals.
As part of the reforms, the Bank has replaced its 14-day Open Market Operations instrument with a seven-day instrument and narrowed the policy corridor from plus or minus 400 basis points to plus or minus 100 basis points around the policy rate.
The adjustment comes as Ghana’s economic activity remains strong, with the Bank’s Composite Index of Economic Activity recording growth of 17.7% year-on-year in September 2026, compared with 9.6% over the same period last year.
The growth was supported by increased private sector credit, exports, tourist arrivals and construction activity.
However, headline inflation edged up to 5.5% in October 2026 from 5.2% in September, largely reflecting an increase in non-food inflation.
Non-food inflation rose to 7.9% from 6.2%, driven mainly by higher utility tariffs and elevated crude oil prices. Food inflation, on the other hand, eased to 2.8% from 4.0%, reflecting improved food supply.
On lending conditions, the average bank lending rate declined to 15.8% in October from 22.2% a year earlier, while private sector credit growth accelerated to 37.2% from 13.9%.
Dr Asiama said the Bank’s assessment showed that there was still room for further private sector credit expansion, adding that the growth in lending had not yet reached a level that threatened liquidity management.
The banking sector also remained solvent, profitable and liquid, with total assets increasing by 21.2% year-on-year to GH¢512.9 billion. The industry’s non-performing loan ratio declined to 13.1% from 19.5%.
Meanwhile, Ghana’s gross international reserves stood at US$12.1 billion as of November 17, 2026, equivalent to 4.4 months of import cover, down from US$13.8 billion at the end of December 2025.
The MPC said it would continue to monitor developments in the domestic and global economy, particularly crude oil prices, food production risks associated with El Niño and adjustments in utility tariffs, which could influence the inflation outlook.